Bitcoin vs Traditional Money: Understanding Supply, Transfers and Custody
Comparisons between Bitcoin and conventional money usually collapse into an argument about whether one is better. That is not a useful frame, because they differ structurally on three specific points and are similar on most others. The three differences are worth understanding on their own terms.
1. Who decides how much exists
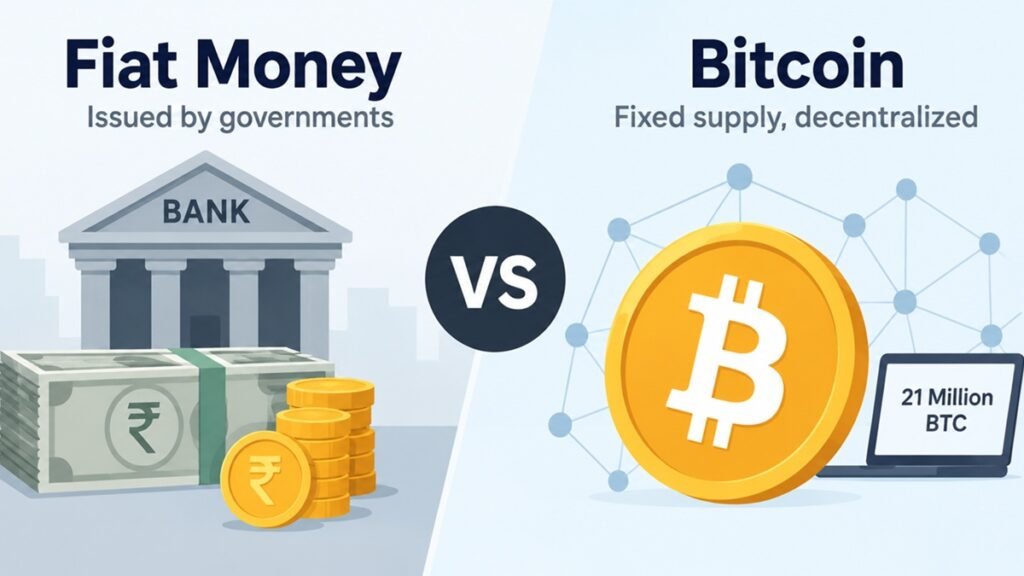
Conventional currency supply is a policy decision. A central bank sets interest rates and conducts operations that expand or contract the money supply, responding to inflation, employment and financial stability. Commercial banks create most of the money in circulation through lending. The quantity is deliberately adjustable, because adjustability is considered a feature: it allows a response to a recession or a crisis.
Bitcoin’s supply is fixed by its software rules. New units are issued to miners at a rate that halves roughly every four years, and issuance stops at 21 million units. No authority can change this without the agreement of the network, which in practice means it does not change.
The trade-off is straightforward and genuinely contested. A fixed supply cannot be debased by decision; it also cannot be adjusted when adjustment would help. The full case on each side is set out in this comparison of Bitcoin vs fiat money.
2. How a transfer actually settles
| Bank transfer | Bitcoin transfer | |
|---|---|---|
| Who executes it | Your bank, through a clearing system | The network, from a signed instruction |
| Settlement | Minutes to days, depending on system | Typically under an hour for practical confidence |
| Reversible | Yes, in defined circumstances | No |
| Hours | Business hours for some systems | Continuous |
| Cross-border | Correspondent banks, fees, delays | Identical to domestic |
| Cost driver | Amount and corridor | Network congestion, not amount |
Reversibility is the difference that matters most in daily life. A bank transfer sent to the wrong account can sometimes be recalled; fraud can be disputed. That protection exists because an institution stands behind the transaction and can unwind it. Bitcoin has no such institution, so the finality is total — a strength for a merchant and a serious hazard for a careless sender.
The fee structure is also counter-intuitive: sending a very large amount costs the same as a small one, because fees depend on transaction size in bytes and current demand for block space, not on value.
3. Who holds it, and what that means
Money in a bank account is a claim on the bank. The bank holds the money; you hold a promise. In most countries that promise is backed by deposit insurance up to a limit, and the bank will help you if you lose your password.
Bitcoin can be held either way. Left on an exchange, it is a claim on that exchange — structurally similar to a bank deposit, without the insurance or the regulation. Held in your own wallet, you control it directly, and you are also the entire support department: lose the key and it is gone, with no process to recover it.
This is the genuine novelty. Conventional money offers no equivalent of direct custody; cash is the closest analogue, and cash does not work over the internet.
Where they are more alike than the arguments suggest
- Both have value because people accept them, not because of intrinsic properties.
- Both are overwhelmingly digital in practice.
- Both are used in ordinary commerce and in crime.
- Both depend on infrastructure most users never think about.
The practical summary
Conventional money is optimised for reversibility, consumer protection and policy flexibility, at the cost of requiring trusted institutions. Bitcoin is optimised for fixed supply, direct custody and censorship resistance, at the cost of finality with no recourse and price volatility that makes it awkward as a unit of account.
Those are engineering trade-offs, not a ranking. Which matters more depends entirely on what you are trying to do.
